Seller Credits vs. Price Reduction: Which Saves a Homebuyer More Money?
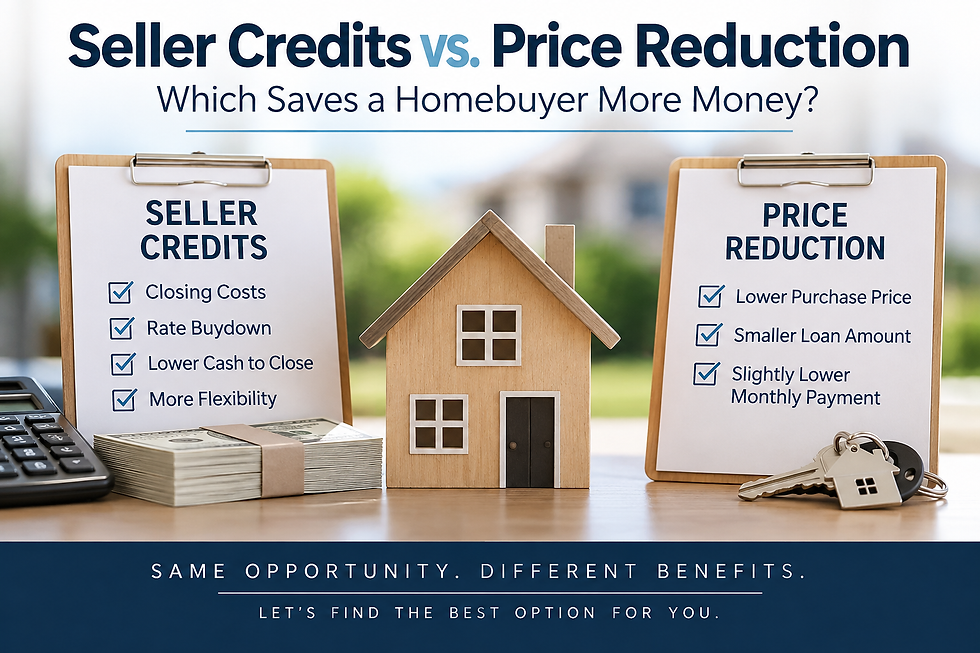
When negotiating the purchase of a home, buyers often focus on one thing: getting the seller to lower the price.
But a lower sales price isn't always the option that saves you the most money.
In some situations, asking the seller for seller credits toward your closing costs or interest rate may provide a much bigger financial benefit than asking for the same amount off the purchase price.
Let's break down the difference.
What Is a Seller Credit?
A seller credit, also called a seller concession, is money the seller agrees to contribute toward certain buyer closing costs.
Depending on the loan program and transaction, seller credits may be used toward eligible expenses such as:
Closing costs
Prepaid property taxes and homeowners insurance
Discount points to lower your mortgage interest rate
Other eligible loan-related expenses
There are limits on how much a seller can contribute, and those limits can vary depending on whether you're using a Conventional, FHA, VA, or USDA loan.
What Is a Price Reduction?
A price reduction simply lowers the amount you're paying for the home.
For example, if you're purchasing a home for $400,000 and negotiate a $10,000 price reduction, your new purchase price would be $390,000.
That sounds like a substantial savings — and it is — but it doesn't mean your monthly mortgage payment will drop by $10,000 worth of savings.
Your loan amount may only decrease by a portion of that $10,000, depending on your down payment.
As a result, the difference in your monthly principal and interest payment may be smaller than you expect.
Why Seller Credits Can Sometimes Be More Valuable
Let's say a seller is willing to negotiate $10,000.
You may have two choices:
Option 1: Reduce the purchase price by $10,000
or
Option 2: Keep the purchase price the same and receive a $10,000 seller credit
With the price reduction, you may finance slightly less and have a somewhat lower monthly payment.
With the seller credit, however, you may be able to use that money toward eligible closing costs or potentially use part of it to buy down your mortgage interest rate.
That could reduce the amount of money you need to bring to closing and, depending on the rate options available, potentially lower your monthly mortgage payment as well.
For many buyers, keeping thousands of dollars in their bank account at closing can be more valuable than a relatively small reduction in the monthly payment.
Here's the Part Buyers Often Miss
A $10,000 reduction in home price does not mean you're saving $10,000 in cash at closing.
If you're financing most of the purchase, you're simply borrowing a little less money.
But a $10,000 seller credit could potentially cover thousands of dollars in eligible closing costs that otherwise would have to come directly out of your pocket.
That's why I always recommend looking at the complete mortgage numbers before deciding how to structure an offer.
What About Using Seller Credits to Buy Down the Interest Rate?
This is another strategy worth comparing.
Seller credits may be used to pay discount points for a lower mortgage rate, subject to loan-program requirements and available pricing.
A lower interest rate can reduce your monthly principal and interest payment.
But buying down the rate isn't automatically the best choice either.
I like to compare:
How much does the lower rate cost?
How much does it actually save each month?
How long will it take to recover that cost?
Sometimes paying points makes sense. Other times, keeping more cash available for moving expenses, repairs, furniture, emergencies, or simply maintaining savings can be the better fit for the buyer's situation.
There Isn't One Right Answer
The best way to structure seller negotiations depends on your specific numbers.
Your purchase price, down payment, loan program, mortgage rate, available seller concessions, property taxes, homeowners insurance and closing costs all matter.
That's why two buyers purchasing homes at the exact same price could benefit from completely different strategies.
Before automatically asking a seller to reduce the sales price, ask your mortgage lender to run the numbers several ways.
You may want to compare:
Price reduction vs. seller-paid closing costs vs. interest-rate buydown.
Sometimes the option that looks best on the purchase contract isn't the one that saves you the most money.
Buying a Home in Texas? Let's Run the Numbers.
If you're buying a home in Cypress, Houston, Harris County, Montgomery County, or anywhere in Texas, I can help you compare your mortgage options before you decide how to structure your offer.
Whether you're a first-time homebuyer, move-up buyer, veteran, investor, or purchasing new construction, I'll help you look beyond just the interest rate and purchase price so you can understand the actual numbers.
At Cypress Mortgage Pro, I help Texas homebuyers compare Conventional, FHA, VA, USDA and other mortgage loan options, including down payment choices, seller credits, interest-rate buydowns, estimated closing costs and monthly mortgage payments.
Have a home in mind?
Send me the purchase price, estimated taxes, HOA information and how much you're planning to put down, and I can help you compare different financing scenarios.
Jennifer No RMLO
C&T Mortgage, Inc18739 Mueschke Rd Ste B Cypress, TX 77433
Office: 832-220-1480
Cell: 936-525-7225
Company NMLS: 1231852Individual NMLS: 1310829
Loan programs, interest rates, seller contribution limits and qualification requirements are subject to change and may vary based on loan program, borrower qualifications and property type. Contact me for information specific to your financing scenario.


Comments